For NRIs, a Fixed Deposit can provide a structured way to park money in India for a defined period. However, choosing between an NRE fixed deposit and an NRO fixed deposit involves more than comparing interest rates. The source of the funds, taxation, repatriation and intended use.
Understanding these differences can help NRIs select a deposit structure that fits their financial requirements.
What Is an NRE Fixed Deposit?
An NRE fixed deposit is a rupee-denominated term deposit designed for eligible NRIs and funded through permitted overseas remittances or eligible transfers from NRE or FCNR(B) Accounts.
Under RBI rules, NRE deposits are generally repatriable. Interest earned on an NRE deposit is generally exempt from Indian income tax, subject to applicable conditions.
This can make an NRE deposit relevant when an NRI wants to bring overseas earnings into India, earn interest on them and retain the ability to repatriate the funds.
What Is an NRO Fixed Deposit?
An NRO fixed deposit is intended primarily for funds connected with income and transactions in India. An NRO Account can receive permitted Indian income such as rent, dividends, pension and interest.
Interest on an NRO fixed deposit is taxable in India, with TDS applicable according to prevailing rules. Repatriation of NRO balances is subject to applicable RBI conditions and prescribed limits.
An NRO deposit can therefore be useful when an NRI wants to earn returns on eligible Indian-source funds rather than leaving the entire balance in a savings account.
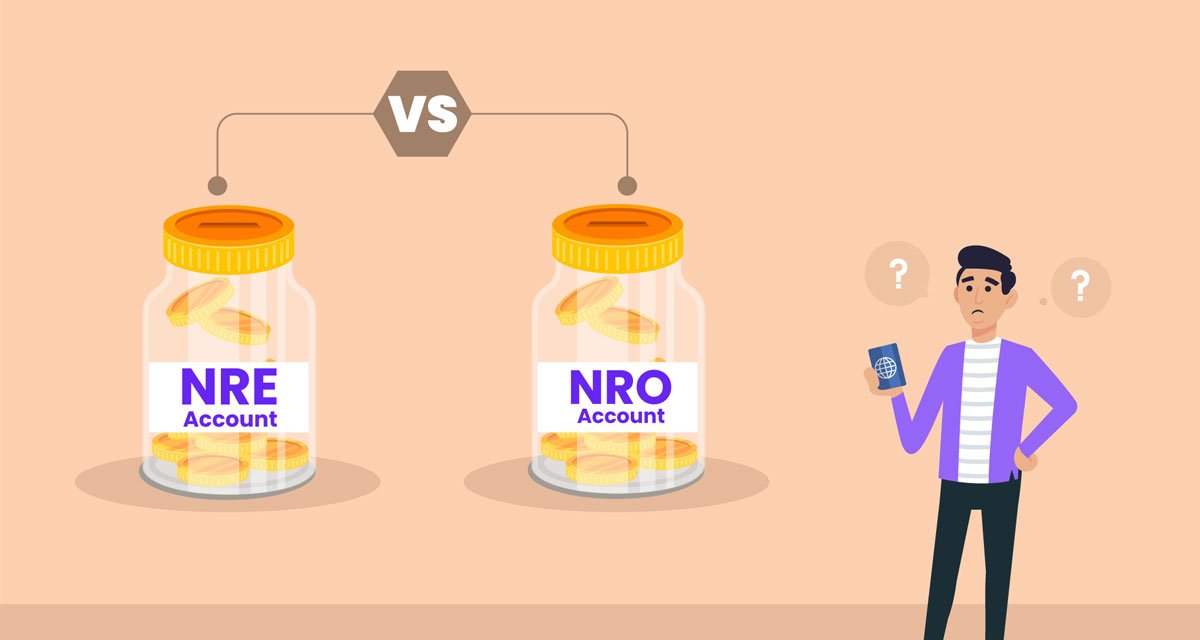
NRE vs NRO Fixed Deposit
| Feature | NRE Fixed Deposit | NRO Fixed Deposit |
| Primary purpose | Overseas earnings | Indian-source funds |
| Currency | Indian Rupees | Indian Rupees |
| Interest taxation | Generally exempt, subject to conditions | Taxable with applicable TDS |
| Repatriation | Generally permitted | Subject to applicable rules |
| Suitable for | Eligible overseas funds | Eligible Indian income and balances |
RBI permits NRE deposits for terms of one to three years, while banks may accept deposits beyond three years based on their asset-liability requirements. NRO Fixed Deposits follow the applicable terms for NRO deposits and the individual bank’s product conditions.
Which Deposit Fits Different Goals?
The source of money is an important starting point.
If the funds originate from overseas earnings and are intended to remain available for repatriation, an NRE fixed deposit may fit the requirement. If the money comes from rental income, pension, dividends or other legitimate Indian receipts, an NRO Fixed deposit may be more appropriate.
The investment horizon also matters. Before choosing either option, check the tenure, maturity instructions and premature withdrawal conditions. Banks formulate policies governing premature withdrawal, and the interest payable can change if a deposit is closed before maturity.
Factors to Check Before Booking
Consider these points before placing funds in an NRI fixed deposit:
- Source of funds: Determine whether the money originates overseas or in India.
- Taxation: Compare the applicable tax treatment of interest.
- Repatriation: Check how easily the principal and interest can be transferred overseas.
- Tenure: Match the deposit period with your financial goal.
- Premature withdrawal: Review applicable penalties and interest adjustments.
- Currency risk: Both NRE and NRO fixed deposits are rupee-denominated, so overseas investors remain exposed to exchange-rate movements against their home currency.
Final Takeaway
An NRE fixed deposit and an NRO fixed deposit are designed for different financial circumstances. NRE deposits generally suit eligible overseas funds and offer broad repatriability with tax-exempt interest which are subject to conditions. NRO deposits are designed primarily around Indian-source funds, with taxable interest and regulated repatriation.
The appropriate choice depends on the source of your money, tax position, liquidity needs and future plans. Comparing these factors alongside the interest rate can provide a more complete picture of the deposit’s suitability.
FAQs
1. What is an NRE fixed deposit?
It is a rupee-denominated term deposit for eligible NRIs, generally funded through permitted overseas remittances or eligible NRE and FCNR(B) transfers.
2. What is an NRO fixed deposit?
It is a term deposit created from eligible NRO funds and is generally used for managing Indian-source income and balances.
3. Is NRE fixed deposit interest taxable in India?
It is generally exempt from Indian income tax, subject to applicable conditions.
4. Is NRO fixed deposit interest taxable?
Yes. Interest is taxable in India, with applicable TDS.
5. Can NRO fixed deposit proceeds be repatriated?
Repatriation is permitted subject to applicable RBI rules, documentation, tax compliance and prescribed limits.
Keyword Usage
| Keyword | Usage |
| nre fixed deposit | 7 |
| nro fixed deposit | 7 |